KHTS Radio Santa Clarita Radio – Santa Clarita News

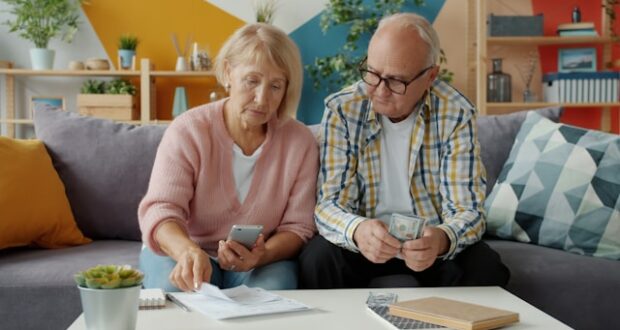
A comfortable retirement depends on more than reaching a savings goal. Seniors can still face financial strain when their plans overlook changing expenses, taxes, insurance policies, and unexpected events.
Regularly reviewing each part of the plan can uncover money-saving opportunities and prevent expensive surprises. A few practical adjustments may provide greater flexibility throughout retirement.
Underestimating Healthcare Costs
Medicare helps with many expenses. But premiums, deductibles, dental treatment, hearing aids, prescriptions, and long-term care can place significant pressure on a fixed income.
Retirees often spend thousands on health care during retirement. Seniors who budget only for basic Medicare premiums could therefore face a substantial shortfall.
You should review coverage and expected out-of-pocket costs annually. Building a separate healthcare reserve can also prevent medical bills from disrupting money intended for housing and daily living.
Keeping an Unwanted Life Insurance Policy
Your life insurance policy may no longer match your needs as a senior. And rising premiums can quietly reduce retirement cash flow. Yet many policyholders assume their only choices are paying, surrendering, or allowing the coverage to lapse.
However, sellers eligible for settlement have the opportunity to transfer the ownership of their policies in exchange for a lump-sum payment, which may be considerably higher than the cash-surrender value.
The process generally includes submitting policy and health information before receiving a free estimate. You can review the offer before accepting.
Accepted offers transfer ownership and future premium obligations to the buyer. Payouts can be as much as six to eight times the cash-surrender value.
Ignoring Taxes
Withdrawals from traditional IRAs and many workplace plans are generally taxable. Required minimum distributions can increase taxable income, affect Medicare premiums, and create an unwelcome bill when no money was reserved for taxes.
Seniors should estimate the tax impact before making large withdrawals. Coordinating distributions across taxable, tax-deferred, and tax-free accounts may help keep yearly income more stable.
Annual meetings with a qualified tax or financial professional can identify useful withdrawal strategies. Reviewing beneficiary designations during the same meeting also keeps estate plans aligned with current wishes.
Failing to Maintain an Emergency Fund
Retirement does not eliminate surprise expenses. Home repairs, family emergencies, vehicle replacement, and sudden travel can force seniors to sell investments during a market decline or rely on high-interest credit cards.
Retirees often experience unexpected spending needs. Without accessible savings, one unplanned bill can disrupt several months of carefully managed spending.
Keep emergency money in a liquid account rather than depending entirely on investments. The right amount varies, but it should cover realistic household risks without being exposed to short-term market swings.
Creating More Financial Flexibility for the Years Ahead
Retirement planning mistakes become more expensive when they remain unnoticed for years. Reviewing healthcare costs, taxes, emergency savings, and unnecessary insurance can help seniors protect both their income and independence.
Financial needs change. So, revisit your plan at least once a year and after major life events.
Was this article helpful? If so, explore some of our other insightful content!